
FOR YOUR NEXT HOME
Buy a home
Explore a purchase using a bank statement income review when traditional documentation does not fit your business.
Your business may be doing better than your tax returns suggest. Explore mortgage options that use eligible bank deposits to help document self-employed income.
Serving Arizona, California, Indiana, Ohio and Texas.
Loan options vary by lender, property and state.
Bank statement loans are not no-documentation loans. Credit, assets, business history, eligible deposits and other lender requirements apply. Not all deposits count as income, and not all applicants qualify.
Tell Ethan what you have in mind.
A personal reply from Ethan
Ethan will review your inquiry and contact you personally to discuss your goals and possible next steps.
Schedule a call with EthanOptional · 20-minute phone call · Opens Google Calendar
Mortgage experience
AZ · CA · IN · OH · TX
Talk directly with Ethan
THE EXPERIENCE, IN THEIR WORDS
A new home. A refinance. A clear next step.
Hear from clients who have worked with Ethan.
FEATURED REFINANCE CLIENT
Review summary Briana describes honest guidance and responsive communication during her refinance.
Refinance client experienceMORE CLIENT EXPERIENCES
REPEAT CLIENT
“Ethan is attentive, straight to the point, knows his stuff and works fast.”
PERSONAL ATTENTION
“He was very attentive and on the ball.”
YOUR HOME. YOUR NEXT STEP.
Start with your business, your goals and the way your income is documented. Ethan can help you understand what to review next.
Discuss my situationExcerpts and separately labeled summaries describe individual experiences, not guaranteed outcomes or results under a bank statement loan program. Ratings are separate platform snapshots, not a combined count of unique clients.
A MORTGAGE THAT STARTS WITH YOUR BUSINESS
Buying your next home or reviewing the mortgage you already have starts with a clear picture of your income and financing goals.
FOR YOUR NEXT HOME
Explore a purchase using a bank statement income review when traditional documentation does not fit your business.

FOR YOUR CURRENT MORTGAGE
Review whether a new mortgage makes sense for your payment, loan term and total financing cost.

FOR YOUR HOME EQUITY
Consider a bank statement cash-out refinance, subject to available equity, loan limits and state restrictions.

FOR THE WAY YOU DO BUSINESS
Understand how the account type, business expenses and ownership can affect the income a lender reviews.
Program eligibility, availability, documentation and terms vary by lender and state. Not all applicants will qualify. This is not a commitment to lend.
WHAT A LENDER WILL LOOK AT
Your business historyDocumented self-employment, business activity and ownership help establish the source of income.
Eligible depositsTransfers, borrowed funds and one-time deposits may be excluded or require explanation.
Expenses and ownershipBusiness account deposits may be adjusted for expenses and your share of the business.
The complete loan fileCredit, debts, assets, reserves, property details and the loan purpose still matter.
Programs may use 12 or 24 consecutive months of personal or business bank statements. Requirements and eligible transactions vary. Texas cash-out restrictions apply; Ethan will confirm available options. Bank statement program information ↗
UNDERSTAND THE INCOME REVIEW
Try a simple business-account illustration. A lender determines which deposits are eligible and which expense and ownership adjustments apply.
The starting 50% expense factor is an example, not a lender requirement or an approved expense ratio. Personal accounts and other programs may be reviewed differently.
BEFORE ADJUSTMENTS
$20,000Eligible deposits per month enteredAFTER YOUR ASSUMPTIONS
$10,000Illustrative monthly business incomeAn illustration only. This is not verified qualifying income, a loan amount or an approval.
Review my actual optionsCalculation: average eligible monthly business deposits × (1 − expense factor) × ownership share; annual illustration = monthly result × 12. The lender verifies eligible income, business history and all required adjustments. Actual results may be lower or unavailable. These inputs stay on this page and are not submitted or saved. Do not enter account numbers or upload statements here.
THE TEAM PIKOFF APPROACH
You don’t need to have every answer before we talk. You just need a starting point.
Find my starting pointTell Ethan whether you want to buy, refinance or explore cash-out, along with a little about your self-employed work.
Discuss your business history, account type, eligible deposits and documentation before comparing available loan options.
When you’re ready, continue through Barrett’s secure application and underwriting process.
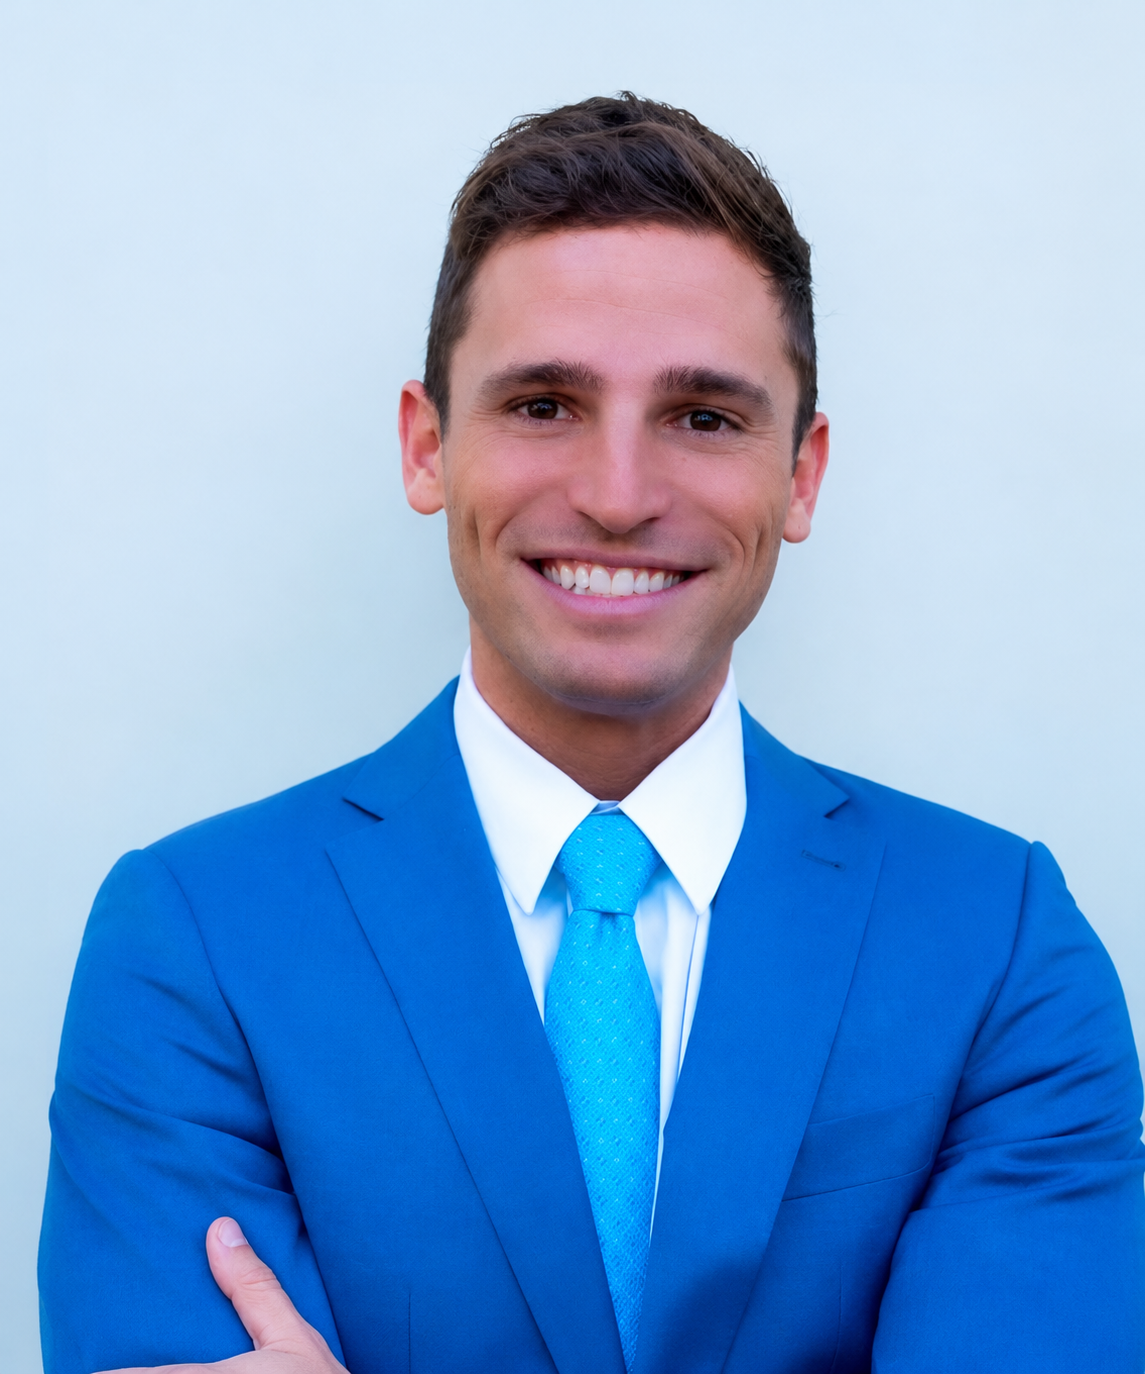
Loan Originator
Barrett Financial Group
A REAL PERSON. A CLEAR PLAN.
Work directly with Ethan—from the first conversation to the next step in your financing.
Running a business can make mortgage paperwork feel more complicated. Ethan helps you understand the bank statement review, the documents a lender may need, and the costs and tradeoffs of your options.
GOOD QUESTIONS. STRAIGHT ANSWERS.
Self-employed income does not always fit a standard checklist. Let’s start with your questions.
Ask Ethan directlyIt is a mortgage option that may use eligible personal or business bank deposits to document self-employed income instead of using tax-return income for that part of qualification. The lender still reviews the complete application and requires supporting documentation.
Business owners, entrepreneurs and other self-employed borrowers whose tax-return income does not fully reflect their current cash flow may want to explore it. Business history, credit, debts, assets and the property are still reviewed. Eligibility depends on the program.
Programs may require 12 or 24 consecutive months. A lender determines the required period, acceptable accounts and whether more documentation is needed. Start with a conversation before sending sensitive financial documents.
Depending on the lender and program, either may be considered. Personal and business accounts are evaluated differently. Business expenses, ownership, transfers and the source of deposits can affect the income allowed.
No. Transfers between accounts, loan proceeds, unusual deposits and other amounts may be excluded or need documentation. A strong deposit total by itself does not establish qualifying income.
Some programs use bank statements in place of tax returns for the self-employed income review. That does not make the loan documentation-free. Business verification, assets, credit and other documents may still be required, and additional income sources may need separate support.
These options may be available under bank statement programs, depending on the lender, property, equity and state. A refinance replaces your current mortgage and may increase the rate, payment or total cost. Texas cash-out restrictions apply; availability must be confirmed.
There is no single requirement across all bank statement programs. Pricing and eligibility depend on credit, the loan amount, property type, equity or down payment, reserves and other factors. Ethan can review the full scenario before discussing available terms.
No. This contact request does not check your credit or authorize a credit report. A formal application and any separate credit authorization take place through Barrett’s application process.
Only your contact details and general goal through this form. Do not include Social Security numbers, account numbers, bank statements or tax returns. Ethan will explain the approved secure process for financial documents.
LET’S LOOK AT THE POSSIBILITIES
Let’s see whether a bank statement loan fits your situation.